Las Cruces Real Estate and Community News

          Hi there! Are you looking to learn more about the Las Cruces area? Between the natural beauty of the area, the historic charm of Mesilla, and our bustling downtown area, there is something for everyone in our amazing city.

              Welcome to our blog, where we're here to help you discover the treasures of Las Cruces, New Mexico. Whether you're a local looking for hidden gems or someone considering making Las Cruces your new home, this blog is your insider's guide to everything our city has to offer. Check out our blog's subcategories to find the specific information you're looking for!

Explore our Site:

Area Information: Discover the Las Cruces area and all that is has to offer. Find out the basics of our town from utility companies to our schools and more.

Farm & Ranch: If you're looking for Farm & Ranch Properties, look no further! Our Farm & Ranch section features our Farm & Ranch Realtor as well as current properties on the market.

Commercial: Looking to invest? Whatever your needs, Commercial listings can be found on this page.

Silver City: If you're interested in buying a property in Silver City we have resources for that as-well! Check out our Area Information page for all the Silver City basics.

Explore our Blog:

Golf Course Communities: Learn more about the various golf course communities residing within Las Cruces.

Area Break Downs: From Mesilla to Pinos Altos Check out all the communities that make up the surrounding areas of Southern New Mexico!


Jan. 29, 2026

Is Las Cruces Still the Right Place to Invest? Part 2: Lifestyle, Education, and Healthcare

Is Las Cruces still the right place to invest? For many, the answer lies in our community’s commitment to health and lifelong learning. In 2026, Las Cruces offers a diverse array of amenities and academic pathways:

  • Diverse Educational Pathways: Las Cruces Public Schools (LCPS) has evolved to meet the needs of a modern workforce. Recent year-end reports show significant academic growth, particularly in literacy and math. Beyond traditional campuses, families can access specialized options like Arrowhead Park Early College High School (located on the NMSU campus), where students can graduate with an associate degree.

  • A Medical Hub: The Burrell College of Osteopathic Medicine continues to expand its impact, training the next generation of physicians right here in the Mesilla Valley. This has significantly bolstered our local healthcare infrastructure, benefiting families and our growing retiree population.

  • Amenities & Culture: From the newly improved East Mesa Public Recreation Complex to the top-ranked Farmers & Crafts Market of Las Cruces, our city prioritizes quality of life. Whether you’re hiking the Organ Mountains or exploring the expanded Thomas Branigan Memorial Library, the "Mesilla Valley lifestyle" is more vibrant than ever.

The Long View: Quality of life is a major driver of property value. As Las Cruces continues to invest in its schools and public spaces, it remains one of the most attractive communities in the Southwest for those seeking a balanced lifestyle.

Find Your Place in Our Community Choosing a home is about more than just square footage—it’s about the morning commute, the right school district, and the lifestyle you want to lead. If you need a local expert to help you navigate our diverse educational pathways and neighborhood amenities, I’m here to guide you. Contact me today for a custom Las Cruces neighborhood guide.

Andrew "Drew" Ahearn, REALTOR® | Associate Broker, Saenz & Smith Real Estate Co

575-323-1482 | drewahearnrealtor@gmail.com | View My Bio Here

Jan. 25, 2026

Is Las Cruces Still the Right Place to Invest? Part 1: The $165B Tech & AI Boom

Is Las Cruces still the right place to invest? As we enter 2026, the data says yes—largely because of our rapidly diversifying economy. While other regions rely on a single industry, the Mesilla Valley is powered by three global pillars:

  • Aerospace, Defense, and AI (Project Jupiter): Doña Ana County is at the center of the $165B Project Jupiter campus in Santa Teresa. With Oracle and OpenAI leading the way, this hyperscale AI data center is projected to create up to 1,500 permanent high-tech roles. Combined with White Sands Missile Range, NASA’s White Sands Test Facility, and Spaceport America, our region is a primary corridor for national security and innovation.

  • A Legacy of Engineering Excellence: New Mexico State University (NMSU) remains a cornerstone of our growth. Recognized as the #1 public university in New Mexico in the 2026 U.S. News & World Report rankings, NMSU’s College of Engineering is nationally ranked and feeds high-level talent directly into our local aerospace and tech sectors.

  • The Remote Work "Sweet Spot": With upgraded fiber infrastructure and a cost of living that remains competitive, we continue to attract "work-from-anywhere" professionals who want mountain views without the big-city price tag.

The Long View: While monthly economic headlines may fluctuate, the long-term infrastructure being built in Southern New Mexico today suggests that Las Cruces is transitioning from a regional hub into a global tech player.

Moving for the Mission? Whether you’re relocating for a role at Project Jupiter, joining the team at NASA, or coming to learn at NMSU, finding the right home base is the first step in your New Mexico journey. I specialize in helping professionals navigate the local market with the data-driven insights you need. Let’s secure your spot in the Mesilla Valley.

Andrew "Drew" Ahearn, REALTOR® | Associate Broker, Saenz & Smith Real Estate Co

(M) 575-323-1482 | (O) 575-386-2363 | drewahearnrealtor@gmail.com | View My Bio Here

Jan. 19, 2026

Las Cruces Real Estate: 2025 Year-End Review & 2026 Market Outlook

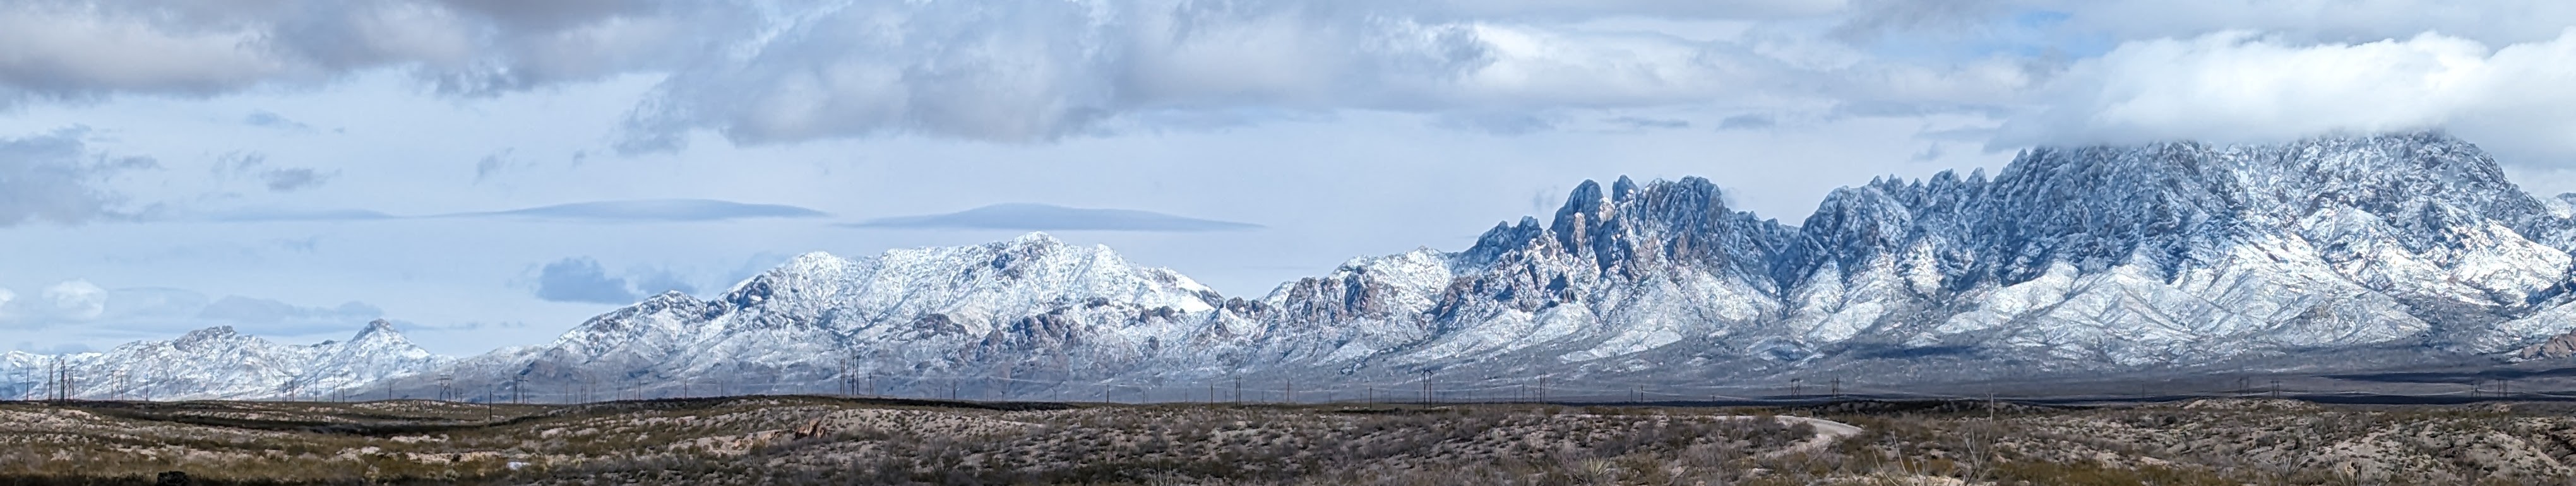
Snow-capped Organ Mountains in Las Cruces, New Mexico - Saenz & Smith Real Estate Market Update

A Look Back at 2025: Stability Returns to the Mesilla Valley

As we kick off 2026, the Las Cruces real estate market is sending a clear message: The "frenzy" is over, but the market is healthier than ever. According to the latest year-end data from the Southern New Mexico MLS, we are seeing a shift toward a more balanced market. While the record-breaking price spikes of the early 2020s have leveled off, buyer activity is surging as people find more options and more time to make decisions.


📊 By The Numbers: December 2025 Market Snapshot

Using the latest Domus Analytics for our region, here is how the market performed as we closed out the year:

Metric (Residental) Dec 2025 Value Change vs. Dec 2024
Median Sales Price (Single Family) $320,670 📉 -4.3%
Closed Sales 231 📈 +20.3%
Median Days on Market 62 Days 📈 +31.9%
Months Supply of Inventory 4.8 Months 📉 -12.7%
List Price Received 96.8% 📉 -0.5%

3 Key Takeaways for Las Cruces Residents


1. Buyers Have More Negotiating Power

For the first time in several years, the "List Price Received" has dipped to 96.8%. This means the average buyer is successfully negotiating about 3% off the asking price. Combined with a 62-day median time on market, buyers no longer have to make split-second decisions and can finally include contingencies that protect their interests.


2. Sales Volume is Surging

Despite a slight dip in the median sales price to $320,670 for single-family homes, the number of homes sold jumped by 20.3% compared to last December. People are moving! This indicates that the "lock-in effect" of previous years is thawing, and more families are deciding that 2026 is the year to find their dream home.


3. We Are Approaching a "Balanced" Market

Real estate experts generally consider a 5 to 6-month supply of inventory to be a "balanced" market (favoring neither buyer nor seller). At 4.8 months of supply, Las Cruces is closer to a balanced market than we have been in nearly a decade. This is great news for the long-term health of our community.


What This Means for You

  • Considering Selling? Your home is likely worth significantly more than it was 5 years ago, but the "selling window" has widened. Expect your home to stay on the market for about two months and be prepared to negotiate on price or repairs to seal the deal.

  • Considering Buying? With 1,109 active listings in the area, you have choices! The slight dip in year-over-year prices represents a "buy the dip" opportunity before the spring rush begins.

The Long View: While monthly prices may fluctuate, the 10-year trend for Las Cruces remains incredibly strong. Since 2016, our community has seen consistent growth, proving that the Mesilla Valley remains a premier place to invest in a home.

Ready to make a move in 2026?

Whether you are looking for your first home or planning to sell for the best possible price, having an expert who understands these local numbers is your greatest advantage.

Contact me today to discuss your real estate goals.

Andrew "Drew" Ahearn, REALTOR ®

Associate Broker, Saenz & Smith Real Estate Co.

575-323-1482

drewahearnrealtor@gmail.com

Check out my Bio here: https://www.saenzsmith.com/Drew/


Posted in Market Updates
April 1, 2024

Community Spotlight: Papen-Aprendamos Autism Diagnostic Center

          Today, in the spirit of April being Autism Awareness Month, we're highlighting the Papen-Aprendamos Autism Diagnostic Center, a vital resource serving southern New Mexico. Founded through collaborative efforts and generous contributions, this center stands as a beacon of support for individuals and families affected by autism. 

          At the Papen-Aprendamos Autism Diagnostic Center, their mission is clear: to provide comprehensive evaluations and support services for individuals of all ages, ensuring timely and accurate diagnoses. Beyond diagnosis, the center offers innovative programs and training initiatives, empowering both NMSU students and community organizations with the tools and knowledge needed to navigate autism effectively.

          Led by Abel Covarrubias and supported by community leaders like former state Senator Mary Kay Papen, the center's impact extends far beyond its walls. Through transformative initiatives and scholarships, it fosters a culture of compassion and service, reflecting a commitment to making a meaningful difference in the lives of those it serves.

          As the only center of its kind in southern New Mexico, the Papen-Aprendamos Autism Diagnostic Center plays a crucial role in providing hope, understanding, and support to our community. We're proud to stand behind this essential resource and its dedication to creating a brighter future for individuals with autism and their families.

          To learn more check out their Facebook page or click here for their NMSU page. OR you can watch the video below to see our spotlight with Adam's radio!


Posted in Community Corner
March 25, 2024

Community Spotlight: Grajeda-Huckaby Low Barrier Housing Fund

          At Saenz & Smith, we're dedicated to actively participating in and supporting our community. Through our recent collaboration with Adam's Radio, we've found an excellent platform to not only showcase our brokerage but also spotlight the remarkable projects and organizations that make our community thrive. This partnership isn't just about promoting ourselves – it's about shining a light on the vital work being done right here in our backyard.

          The Grajeda-Huckaby Low Barrier Housing Fund is a newly created organization that helps fulfill the need for immediate housing support. While there are many programs that provide housing for individuals in need, The Grajeda-Huckaby Low Barrier Housing Fund works to fulfill gaps in these preexisting programs. Rather than provide on-going housing this project works to provide temporary housing for various reasons.

           To find out more information about the fund you can click here or here to make a donation, or you can watch the video below to see our spotlight with Adam's radio!

Posted in Community Corner
March 12, 2024

Downsizing: Finding the Perfect Home for Aging in Place

          As we age, our housing needs may change. For many older adults, downsizing to a more manageable home becomes a practical and necessary step to maintain independence and quality of life. In this blog post, we'll explore the importance of downsizing to homes without stairs, with smaller yards, and featuring accessibility features like handrails, to create a safe and comfortable living environment for aging in place.

Why Downsizing Matters:

Enhanced Safety and Accessibility:

  • Downsizing to a home without stairs reduces the risk of falls and injuries, particularly for older adults with mobility issues or disabilities.
  • Eliminating stairs also makes it easier to navigate the home and reduces the likelihood of accidents, especially during nighttime trips to the bathroom or kitchen.
  • Accessible features such as handrails, grab bars, and no-step entries further enhance safety and promote independence for older adults with mobility challenges.

Reduced Maintenance and Upkeep:

  • Maintaining a large home with multiple floors and a sprawling yard can become overwhelming as we age, leading to increased stress and physical strain.
  • Downsizing to a smaller home with a more manageable yard reduces the time and effort required for maintenance tasks such as cleaning, landscaping, and repairs.
  • By minimizing maintenance demands, older adults can enjoy more leisure time and focus on activities that bring them joy and fulfillment.

Improved Quality of Life:

  • Downsizing allows older adults to simplify their living environment and declutter their possessions, leading to a more organized and stress-free lifestyle.
  • Smaller homes often offer cozier living spaces that are easier to maintain and provide a greater sense of comfort and security.
  • Access to amenities such as community centers, parks, and walking trails in downsized neighborhoods can enhance social connections and overall well-being.

Financial Benefits:

  • Downsizing can free up equity from the sale of a larger home, providing older adults with additional financial resources for retirement, healthcare expenses, or travel.
  • Smaller homes typically have lower utility bills, property taxes, and insurance costs, resulting in reduced monthly expenses and greater financial stability.
  • By downsizing to a more affordable home, older adults can stretch their retirement savings further and enjoy a more comfortable standard of living.

Features to Look for in a Downsized Home:

Single-story layout:

  • Bedrooms, bathrooms, kitchen, and laundry facilities should ideally be located on the same level to eliminate the need to navigate stairs.
  • Look for wide hallways and doorways that can accommodate mobility aids such as walkers or wheelchairs.
  • Consider homes with open floor plans that provide plenty of space for maneuvering and allow for flexible furniture arrangements.

Smaller yard:

  • Seek out homes with low-maintenance landscaping options such as drought-tolerant plants, gravel or mulch beds, and native vegetation.
  • Look for properties with smaller outdoor living spaces that still offer opportunities for gardening, entertaining, or relaxation.
  • Consider homes with paved patios, decks, or courtyard areas that provide outdoor space without the need for extensive upkeep.

Accessibility features:

  • Install handrails or grab bars in key areas such as bathrooms, hallways, and staircases to provide added stability and support.
  • Choose homes with no-step entries or ramps leading to the front door to ensure easy access for individuals with mobility challenges.
  • Look for bathrooms with roll-in showers, adjustable showerheads, and non-slip flooring to create a safer bathing experience.
  • Consider homes with lever-style door handles, rocker light switches, and other accessible fixtures that are easier to operate for individuals with limited dexterity.

Working with a Real Estate Agent:

 Specialized expertise:

  • Seek out real estate agents who have experience working with older adults and are knowledgeable about accessible housing options.
  • Look for agents who have earned certifications or designations such as Seniors Real Estate Specialist (SRES) or Certified Aging-in-Place Specialist (CAPS) to ensure they understand your unique needs and preferences.
  • Consider agents who are familiar with local resources and services for older adults, including home modification specialists, aging-in-place contractors, and community support programs.

Personalized assistance:

  • Communicate your specific needs and preferences to your real estate agent, including any mobility challenges, accessibility requirements, or lifestyle preferences.
  • Work with your agent to create a customized search criteria that prioritizes homes with the features and amenities that are most important to you.
  • Take advantage of your agent's expertise and guidance throughout the homebuying process, from viewing properties to negotiating offers and closing the deal.

Local market knowledge:

  • Rely on your agent's local market knowledge to identify neighborhoods and communities that offer accessible amenities, services, and resources for older adults.
  • Ask your agent for information about local transportation options, healthcare facilities, recreational activities, and other factors that may influence your decision to downsize.
  • Trust your agent to provide valuable insights and advice based on their understanding of the local real estate market and trends affecting older adults.

          Downsizing to a home without stairs, with a smaller yard, and featuring accessibility features like handrails is an important step in creating a safe and comfortable living environment for aging in place. By prioritizing these features and working with a knowledgeable real estate agent, older adults can find a downsized home that meets their needs and allows them to continue living independently for years to come.

Posted in Homeowner Hub
March 4, 2024

Creating a Safe and Accessible Home for Older Adults

            As we age, our homes should evolve to meet our changing needs. For older adults, ensuring home safety and accessibility is paramount to maintaining independence and quality of life. In this guide, we'll explore practical tips and resources for creating a safe and accessible home for aging in place. Let's dive in!

1. Fall Prevention:

Understand the risks: Falls are a leading cause of injury among older adults, but many are preventable with proper precautions.

Create a safe environment: Remove tripping hazards, install grab bars and handrails, and improve lighting to reduce the risk of falls.

Stay active: Regular exercise can improve strength, balance, and flexibility, reducing the risk of falls and promoting overall health.

2. Home Modifications for Aging in Place:

Bathroom safety: Install grab bars in the shower and near the toilet, use non-slip mats, and consider a walk-in shower or bathtub for easier access.

Kitchen accessibility: Lower countertops, install pull-out shelves, and use lever-style handles on cabinets and faucets to make the kitchen more user-friendly.

Bedroom and living areas: Ensure clear pathways, remove clutter, and consider adjustable beds and furniture with built-in storage for added convenience.

3. Community Resources for Seniors:

Local senior centers:

These centers offer a variety of social activities, educational programs, and support services tailored to older adults. Activities may include fitness classes, arts and crafts, educational workshops, and group outings. Additionally, senior centers often provide valuable resources and referrals for community-based services.

Aging-in-place programs:

Many communities offer aging-in-place programs designed to help seniors remain independent in their own homes. These programs may provide assistance with home modifications, transportation services, meal delivery, and in-home care. By participating in these programs, older adults can access the support they need to age safely and comfortably in familiar surroundings.

Health and wellness services:

Access to health and wellness services is essential for older adults to maintain their overall well-being. Community resources such as home healthcare agencies, meal delivery programs, and wellness checks can help seniors manage their health needs and stay connected to healthcare providers. Additionally, local organizations may offer educational workshops and screenings on topics such as nutrition, chronic disease management, and medication management.

           Creating a safe and accessible home is essential for older adults looking to age in place with dignity and independence. By implementing practical tips for fall prevention, making home modifications, and accessing community resources, older adults can enjoy a comfortable and secure living environment for years to come. Partnering with local organizations and experts can provide valuable support and resources to help older adults thrive in their homes and communities.

Posted in Homeowner Hub
Feb. 21, 2024

Home Inspection Checklist

           Thinking about buying a home? One crucial step in the home buying process is the home inspection. This checklist will help you understand what to expect during a home inspection and what areas to pay close attention to. Let's get started!

1. Exterior Inspection:

Roof: Check for missing or damaged shingles, signs of leaks, and the overall condition of the roof.

Gutters and Downspouts: Ensure they are clear of debris and properly attached to the house to prevent water damage.

Siding: Look for cracks, holes, or signs of water damage in the siding material.

Foundation: Inspect for cracks, settling, or other signs of structural issues.

2. Interior Inspection:

Plumbing: Test faucets, toilets, and drains for leaks or drainage issues.

Electrical: Check light switches, outlets, and the electrical panel for any signs of damage or malfunction.

HVAC Systems: Test heating and cooling systems to ensure they are working properly.

Appliances: Inspect kitchen appliances, water heater, and other built-in appliances for functionality.

3. Structural Inspection:

Walls and Ceilings: Look for cracks, water stains, or signs of structural damage.

Floors: Check for uneven flooring, squeaks, or signs of water damage.

Windows and Doors: Test windows and doors for proper operation and check for signs of drafts or leaks.

4. Additional Inspections:

Radon Testing: Consider testing for radon, a radioactive gas that can be harmful if present in high levels.

Pest Inspection: Schedule a separate pest inspection to check for signs of infestation or damage caused by pests.

Environmental Hazards: Be aware of potential environmental hazards such as mold, asbestos, or lead paint, and consider additional testing if necessary.

          A thorough home inspection is essential for identifying any issues or concerns with a property before you finalize the purchase. By using this checklist as a guide, you can ensure that your home inspection is comprehensive and helps you make an informed decision about your potential new home.


Posted in Home Buyer Help
Feb. 21, 2024

First Time Home Buyers Guide

          Welcome to the First-Time Homebuyer's Guide! Buying your first home is an exciting journey, but it can also be overwhelming. This guide is here to provide you with the knowledge and resources you need to make informed decisions and achieve your homeownership goals. Let's dive in and explore the world of homeownership together!

1. Understanding Your Financial Readiness

Assessing Your Financial Situation:

  • Evaluate your income, including any regular paychecks, bonuses, or other sources of revenue.
  • Take stock of your savings, including any funds earmarked for a down payment, closing costs, and emergency expenses.
  • Assess your existing debt obligations, such as student loans, car payments, and credit card balances.
  • Check your credit score and review your credit report for any errors or areas for improvement.


Determining How Much House You Can Afford:

  • Calculate your maximum home purchase price based on your income, debt, and desired monthly mortgage payment.
  • Consider additional homeownership expenses, including property taxes, homeowners insurance, utilities, and maintenance costs.
  • Use online mortgage calculators to estimate your monthly mortgage payment based on different loan amounts, interest rates, and loan terms.


Exploring Financing Options:

  • Learn about different types of mortgage loans available to first-time homebuyers, such as FHA loans, VA loans, USDA loans, and conventional loans.
  • Understand the down payment requirements for each type of loan and explore options for down payment assistance programs or grants.
  • Get pre-approved for a mortgage to understand how much financing you qualify for and strengthen your position as a serious buyer in the eyes of sellers.


Next Steps:

  • Gather documentation needed for the mortgage pre-approval process, including pay stubs, W-2s, bank statements, and tax returns.
  • Research reputable mortgage lenders and compare loan offers to find the best terms and interest rates for your financial situation.
  • Consider meeting with a financial advisor or housing counselor for personalized guidance and advice on your home buying journey.

2. Exploring the Home Buying Process

Understanding the Steps Involved:

  • Familiarize yourself with the typical home buying process, which includes pre-approval, house hunting, making an offer, home inspection, appraisal, and closing.
  • Research the laws and regulations governing real estate transactions in your area, including disclosure requirements and timelines for completing various steps.


Working with a Real Estate Agent:

  • Understand the role of a buyer's agent in helping you navigate the home buying process, including providing market insights, scheduling property viewings, and negotiating on your behalf.
  • Research local real estate agents with experience working with first-time homebuyers and consider scheduling interviews to find the right fit.


Searching for the Right Home:

  • Identify your priorities and preferences for your future home, including location, size, layout, amenities, and budget.
  • Utilize online real estate platforms and mobile apps to search for properties that meet your criteria and track market trends in your desired area.
  • Attend open houses and schedule private viewings to tour homes and get a feel for different neighborhoods and property types.


Next Steps:

  • Create a wishlist of must-have and nice-to-have features for your future home to guide your search and decision-making process.
  • Keep an open mind and be prepared to adjust your criteria based on market availability and feedback from property viewings.
  • Communicate regularly with your real estate agent to provide feedback on properties, ask questions, and refine your search based on your preferences.

3. Making an Offer and Negotiating

Understanding the Components of an Offer:

  • Learn about the key components of a purchase offer, including the offer price, contingencies, earnest money deposit, and proposed terms.
  • Work with your real estate agent to draft a competitive offer that reflects your budget, priorities, and preferences while also appealing to the seller.


Strategies for Making a Competitive Offer:

  • Research recent comparable sales (comps) in the area to assess the fair market value of the property and inform your offer price.
  • Consider factors such as the property's condition, time on the market, and seller motivations when determining your offer strategy.
  • Discuss negotiation tactics with your real estate agent, such as offering to cover closing costs or including a personalized letter to the seller to strengthen your offer.


Negotiating with Sellers:

  • Be prepared for counter offers from the seller and collaborate with your real estate agent to formulate a response that addresses your needs and concerns.
  • Maintain open communication with the seller or their representative throughout the negotiation process to foster a positive and collaborative atmosphere.
  • Stay flexible and willing to compromise on certain terms while also advocating for your priorities and protecting your interests as a buyer.


Next Steps:

  • Review the final terms of the purchase agreement with your real estate agent and ensure that all contingencies and deadlines are clearly outlined and understood.
  • Prepare for the next steps in the home buying process, including scheduling a home inspection, completing the appraisal, and finalizing your financing.
  • Stay engaged and proactive throughout the closing process, addressing any issues or concerns that arise and preparing for a smooth transition to homeownership.

4. Navigating the Closing Process

Overview of the Closing Process:

  • Understand the steps involved in the closing process, from finalizing financing to signing the necessary legal documents.
  • Work closely with your real estate agent and mortgage lender to ensure all requirements are met and deadlines are adhered to.


Reviewing Closing Costs:

  • Familiarize yourself with the various closing costs associated with buying a home, including lender fees, appraisal fees, title insurance, and escrow fees.
  • Review the Loan Estimate (LE) provided by your lender and the Closing Disclosure (CD) issued before closing to understand the breakdown of costs and fees.


Closing Day:

  • Prepare for the closing appointment by gathering necessary documents, such as government-issued identification, proof of insurance, and certified funds for closing costs and down payment.
  • Review the closing documents carefully and ask questions about any terms or fees you don't understand.
  • Sign the necessary paperwork to transfer ownership of the property and officially become a homeowner.


Next Steps:

  • Celebrate your homeownership milestone and take time to settle into your new home.
  • Address any post-closing tasks, such as transferring utilities, updating your address with relevant parties, and setting up recurring payments for mortgage and homeowners insurance.
  • Stay in touch with your real estate agent and mortgage lender for any follow-up questions or assistance you may need as you transition to homeownership.

5. Maintaining Your Home and Financial Wellness

Tips for Maintaining Your Home:

  • Establish a routine maintenance schedule for tasks such as HVAC servicing, gutter cleaning, and lawn care to keep your home in good condition.
  • Stay proactive in addressing minor repairs and issues to prevent them from becoming larger and more costly problems down the line.
  • Consider budgeting for a home warranty or emergency fund to cover unexpected repairs or maintenance expenses.


Managing Homeownership Expenses:

  • Create a budget that includes mortgage payments, property taxes, homeowners insurance, utilities, and maintenance costs to ensure you can afford homeownership.
  • Look for opportunities to save money on homeownership expenses, such as refinancing your mortgage to lower your interest rate or shopping around for better insurance rates.
  • Review your budget regularly and adjust as needed to accommodate changes in income, expenses, or financial goals.


Building Equity and Long-Term Financial Planning:

  • Explore strategies for building equity in your home, such as making extra principal payments, increasing your home's value through renovations or improvements, and monitoring market trends.
  • Consider how homeownership fits into your long-term financial goals, such as retirement planning, saving for college tuition, or building wealth through real estate investments.
  • Work with a financial advisor to develop a comprehensive financial plan that aligns with your goals and priorities and ensures your continued financial well-being as a homeowner.

          Congratulations on completing the First-Time Homebuyer's Guide! We hope it has provided you with valuable insights to navigate the process successfully. Remember, with careful planning and expert guidance, you'll soon be settling into your new home. Best wishes on your journey to homeownership!


Posted in Home Buyer Help
Feb. 16, 2024

Unlocking Your Mortgage Options

 A Quick Comparison Guide

          Choosing the right mortgage is a crucial but intimidating step on the path to homeownership. With so many options available, it can be overwhelming to know where to start. That's where we come in. This handy guide provides a snapshot of the most common mortgage types, so you can quickly compare key factors like interest rates, down payments, and eligibility criteria. Let's find the perfect mortgage for you!


Fixed Rate Mortgage

Interest Rate: The interest rate remains fixed for the entire term of the loan, providing stability and predictability in monthly payments.

Down Payment Requirements: Typically requires a higher down payment compared to some government-backed loans, often ranging from 5% to 20% of the home's purchase price.

Credit Score Requirements: Generally requires a higher credit score (usually 620 or higher) to qualify for the best interest rates.

Mortgage Insurance: Private mortgage insurance (PMI) may be required for loans with a down payment less than 20% of the home's purchase price.

Loan Term: Common terms include 15, 20, or 30 years, allowing borrowers to choose a repayment period that fits their budget and financial goals.

Advantages: Offers stability and predictability with a fixed interest rate and consistent monthly payments over the life of the loan.

Disadvantages: Initial interest rates may be higher than adjustable-rate mortgages, and borrowers may miss out on potential savings if market interest rates decrease in the future.


Adjustable-rate mortgage (ARM)

Interest Rate: The interest rate is fixed for an initial period (e.g., 5, 7, or 10 years) and then adjusts periodically based on market conditions.

Down Payment Requirements: Similar to fixed-rate mortgages, typically requiring a down payment ranging from 5% to 20% of the home's purchase price.

Credit Score Requirements: Similar to fixed-rate mortgages, generally requiring a credit score of 620 or higher to qualify for the best rates.

Mortgage Insurance: Private mortgage insurance (PMI) may be required for loans with a down payment less than 20% of the home's purchase price.

Loan Term: Similar to fixed-rate mortgages, adjustable-rate mortgages offer various terms to accommodate borrowers' needs.

Advantages: Initial interest rates may be lower than fixed-rate mortgages, potentially resulting in lower initial monthly payments. Borrowers may benefit if market interest rates remain stable or decrease over time.

Disadvantages: Interest rates and monthly payments can increase significantly after the initial fixed-rate period, leading to payment shock and financial strain.


Conventional Loan:

Interest Rate: Interest rates may vary depending on market conditions and the borrower's creditworthiness.

Down Payment Requirements: Typically requires a down payment ranging from 3% to 20% of the home's purchase price, with higher down payments often resulting in lower interest rates.

Credit Score Requirements: Generally requires a higher credit score (usually 620 or higher) to qualify for competitive interest rates.

Mortgage Insurance: Private mortgage insurance (PMI) may be required for loans with a down payment less than 20% of the home's purchase price.

Loan Term: Common terms include 15, 20, or 30 years, providing flexibility for borrowers to choose a repayment period that suits their needs.

Advantages: Offers flexibility in terms of down payment options, loan terms, and interest rates, catering to a wide range of borrowers.

Disadvantages: May have stricter qualification criteria compared to government-backed loans, and borrowers with lower credit scores may face higher interest rates or additional fees.


FHA Loan (Federal Housing Administration):

Interest Rate: Interest rates may vary depending on market conditions and the borrower's creditworthiness, but FHA loans tend to have more lenient requirements for credit scores and down payments.

Down Payment Requirements: Allows for down payments as low as 3.5% of the home's purchase price, making homeownership more accessible to borrowers with limited funds.

Credit Score Requirements: Generally more lenient credit score requirements compared to conventional loans, with minimum credit scores typically ranging from 500 to 580.

Mortgage Insurance: Requires both an upfront mortgage insurance premium (UFMIP) and an annual mortgage insurance premium (MIP), regardless of the down payment amount.

Loan Term: Common terms include 15 or 30 years, providing flexibility for borrowers to choose a repayment period that fits their budget.

Advantages: Lower down payment requirements and more lenient credit score requirements make FHA loans accessible to borrowers with less-than-perfect credit or limited funds.

Disadvantages: Borrowers are required to pay mortgage insurance premiums for the life of the loan, potentially increasing overall loan costs. There are also limits on the maximum loan amount based on the location of the property.


VA Loan (Department of Veterans Affairs):

Interest Rate: Interest rates may vary depending on market conditions and the borrower's creditworthiness, but VA loans tend to offer competitive rates compared to conventional loans.

Down Payment Requirements: Allows for zero-down financing, making homeownership more accessible to eligible veterans, active-duty service members, and qualifying spouses.

Credit Score Requirements: Generally more lenient credit score requirements compared to conventional loans, with no specific minimum credit score requirement set by the VA.

Mortgage Insurance: VA loans typically do not require private mortgage insurance (PMI), even with no down payment, making them more affordable for eligible borrowers.

Loan Term: Common terms include 15 or 30 years, providing flexibility for borrowers to choose a repayment period that suits their needs.

Advantages: Zero-down financing, no private mortgage insurance (PMI) requirement, and competitive interest rates make VA loans an attractive option for eligible veterans and service members.

Disadvantages: Limited eligibility criteria, including military service requirements, may exclude some borrowers from accessing VA loan benefits. There may also be funding fees associated with VA loans, although these can often be financed into the loan amount.


USDA Loan (United States Department of Agriculture):

Interest Rate: Interest rates may vary depending on market conditions and the borrower's creditworthiness, but USDA loans tend to offer competitive rates compared to conventional loans.

Down Payment Requirements: Allows for zero-down financing for eligible properties located in designated rural areas, making homeownership more accessible to qualified borrowers.

Credit Score Requirements: Generally more lenient credit score requirements compared to conventional loans, with minimum credit scores typically ranging from 640 to 660.

Mortgage Insurance: USDA loans require both an upfront guarantee fee and an annual fee for mortgage insurance, but the upfront fee can often be financed into the loan amount.

Loan Term: Common terms include 15 or 30 years, providing flexibility for borrowers to choose a repayment period that fits their budget.

Advantages: Zero-down financing, competitive interest rates, and more lenient credit score requirements make USDA loans an attractive option for eligible borrowers purchasing homes in rural areas.

Disadvantages: Property eligibility requirements based on location may limit options for homebuyers, and there may be income limits for borrowers depending on the area's median income. Additionally, USDA loans require mortgage insurance premiums, which can increase overall loan costs.


Additional Considerations:

Closing Costs: Estimate the closing costs associated with each type of mortgage.

Prepayment Penalties: Check for any penalties for paying off the mortgage early.

Market Conditions: Stay informed about current market conditions and how they may impact interest rates and availability of mortgage options.

Qualification Process: Understand the mortgage application and approval process for each type of loan.


          Choosing the right mortgage is a significant decision that requires careful consideration of various factors. While this guide provides an overview of key factors to consider, we recommend consulting with one of our experienced real estate agents, a mortgage lender, or a financial advisor to explore your options further and determine the best mortgage for your individual needs. Realtors have extensive knowledge of the local market and can provide valuable insights tailored to your specific situation. With the right guidance, you can make an informed decision and embark on your homeownership journey with confidence.

Posted in Home Buyer Help